You’ve been following networking long enough to know that every vendor eventually claims to be an AI company. The trick is figuring out which ones are actually changing their business and which ones are just updating their PowerPoint templates.
Extreme Networks’ first quarter FY27 results suggest the company is trying to do something more significant than selling faster Wi-Fi and attaching AI marketing language to the box. The real story isn’t the 10% revenue growth or even the 50% increase in non-GAAP EPS. It’s that Extreme increasingly wants investors and customers to think of the company as a platform provider rather than a networking hardware vendor. There is no denying that Extreme’s numbers support that argument.
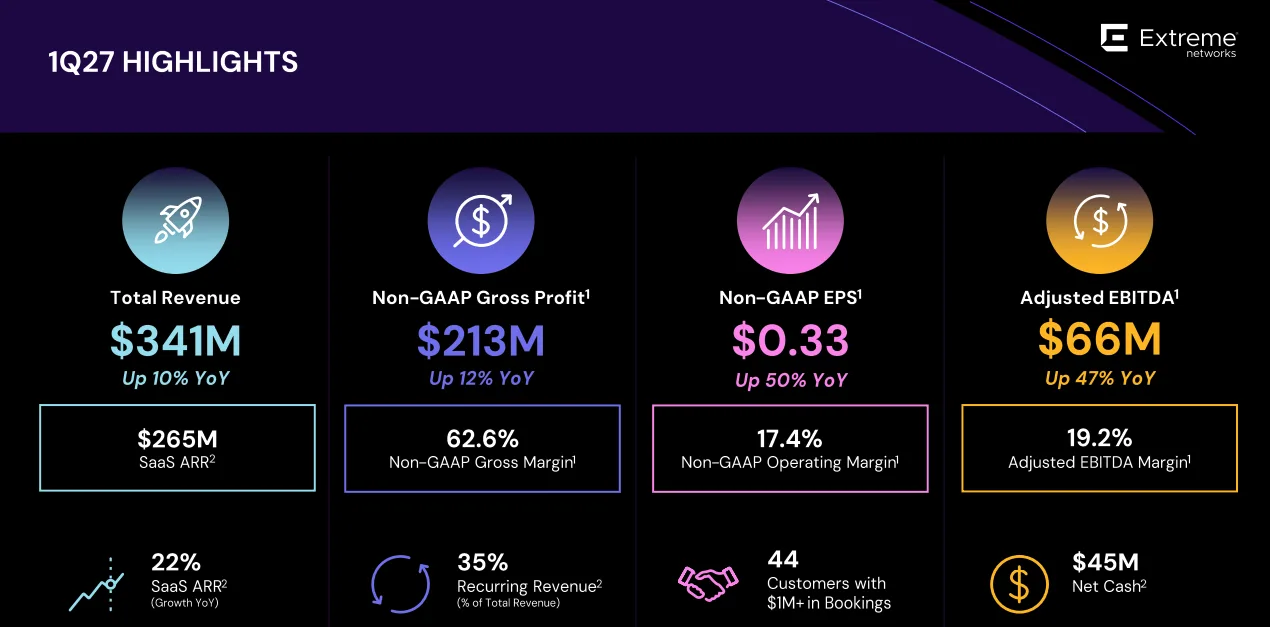
Revenue grew 10% year-over-year to $341 million, marking the seventh consecutive quarter of double-digit growth. SaaS ARR increased 22% to nearly $265 million. Non-GAAP operating margin expanded to 17.4%, showing the company is generating meaningful leverage as software becomes a larger portion of the business. Those are strong results.
Let’s be honest. Lots of networking companies can post a good quarter. In fact, the networking industry is doing pretty well right now. What caught my eye with Extreme was management’s noting that Platform ONE has already crossed the 50% mark for total subscription bookings- roughly a 5X leap compared to this time last year. The company also told analysts it expects more than half of its customers to be on Platform ONE by the end of FY27. I think we are moving beyond this just being an early-adopter story.
From a practitioner perspective, this matters because customers rarely wake up one morning and decide they need another management console. Despite chasing the single pane of glass for 20-plus years, most IT teams have ended up with a stained glass window. If customers are migrating to Platform ONE, they’re making a decision that the operational benefits are worth the disruption. They see this as a much bigger deal than a Wi-Fi refresh.
The other theme emerging from the earnings call is competitive displacement. Extreme continues to highlight wins against larger incumbents, and management openly discussed opportunities created by customer frustration with unnamed competitors (AKA Cisco) as well as uncertainty surrounding the integration of a big networking merger (AKA HPE-Juniper). Analysts pressed management on this point repeatedly, which tells you the Street sees it as a real source of growth rather than conference-call bravado.
I’d compare this dynamic to changing lanes on a crowded Houston freeway. Nobody changes lanes because they’re bored. They change lanes because traffic in the current lane has stopped moving. Enterprise customers behave the same way. They rarely replace networking platforms because they want a project. They replace them because the current path isn’t getting them where they need to go.
Extreme’s opportunity isn’t necessarily convincing enterprises that it’s dramatically better than every competitor. Sometimes the opportunity is simply being in the lane that’s moving.
The AI story is really worth watching. Early engagement with Agent ONE Coworker reportedly ran about ten times higher than the company’s first-generation AI offering. That’s interesting, but investors will eventually want to see AI drive measurable revenue, not just higher click counts and impressive demos.
What really caught my attention is that Platform ONE is becoming the center of the company’s strategy and, increasingly, the center of customer buying decisions. This is much more significant than simply reporting a solid quarter of revenue growth.
The networking market doesn’t need another company selling ports and packet pushers. It already has plenty of those. What Extreme is betting is that the next networking battle will be won by whoever owns the operational platform.